Reconciliation close audit
The month-end pack that explains its own differences. Forty-one ledger rows, forty source rows, five findings, and a variance that ties to the cent.
Month-end reconciliation fails in a specific way: the totals do not tie, and the person holding the pack has no ordered list of why. The difference might be a missing source row, a duplicate ledger entry, a twelve-dollar mismatch, or a sync that stopped nine days ago. This build matches the two extracts, names every difference, ranks it by impact, and sends material findings for a person to sign off.
The brief
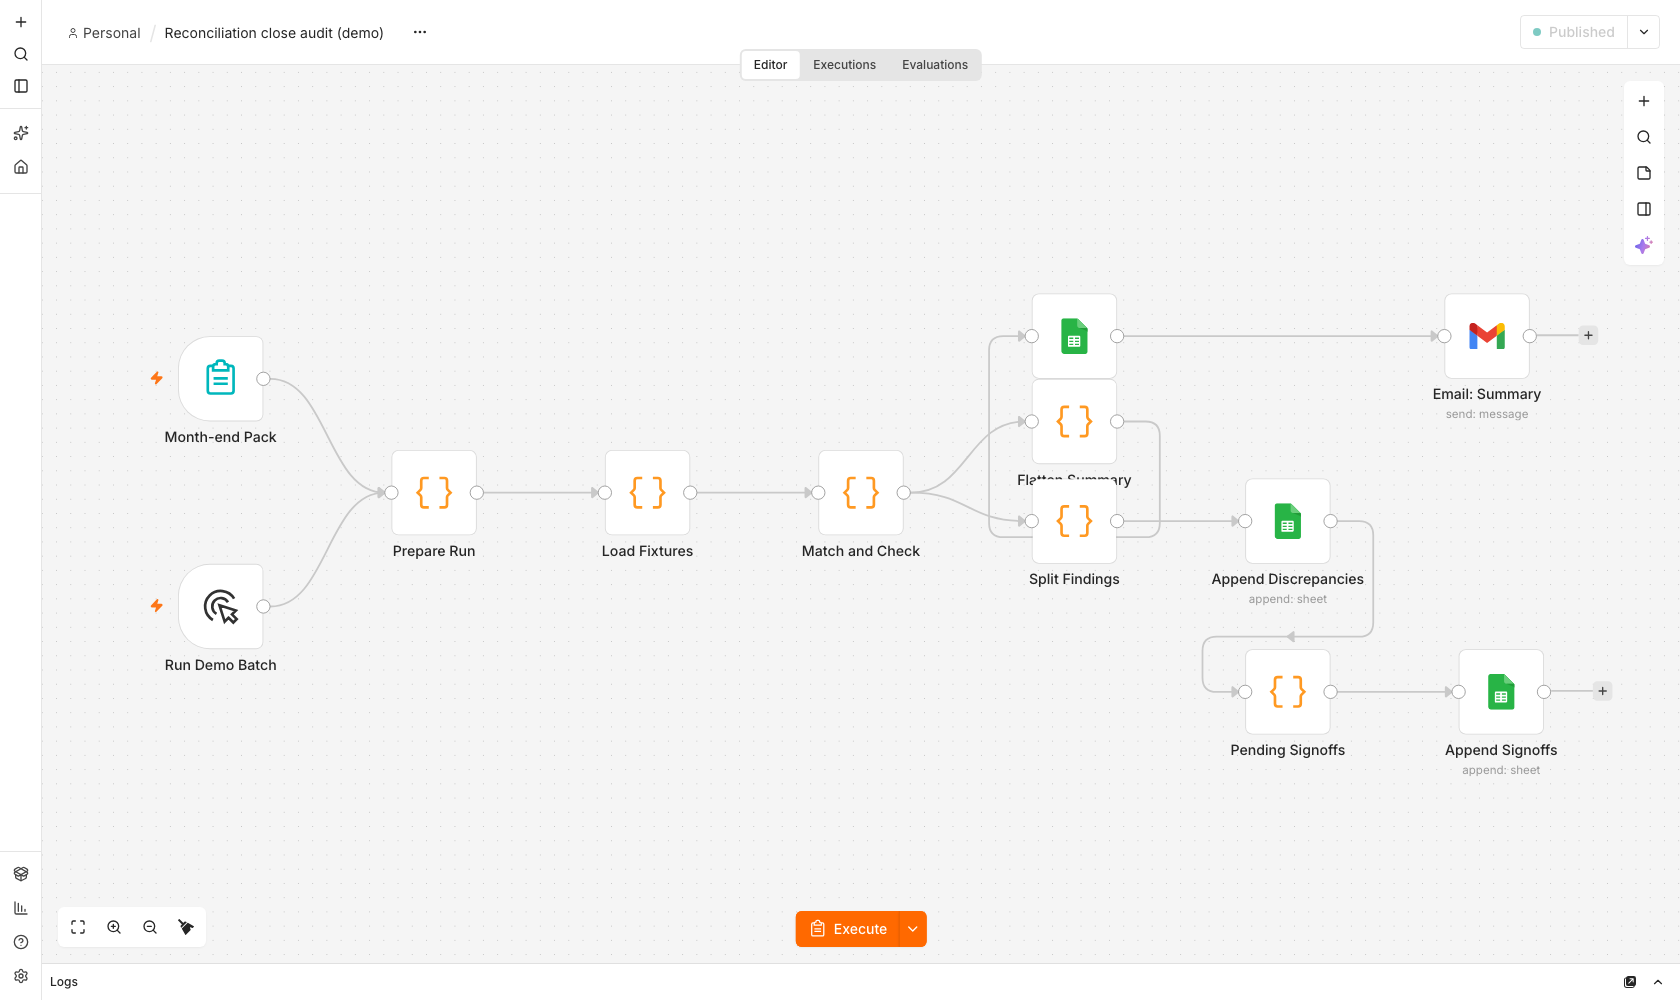
A form starts the run: period, materiality threshold, source label. The audit loads the ledger export and the source-system export, normalises both to one shape, matches on the invoice reference, and runs deterministic checks. Every finding carries the reference, the side it came from, the amount it affects and a plain description. Findings above the materiality threshold become pending sign-offs; nothing is marked reconciled until a person decides.
Evidence from the demo run
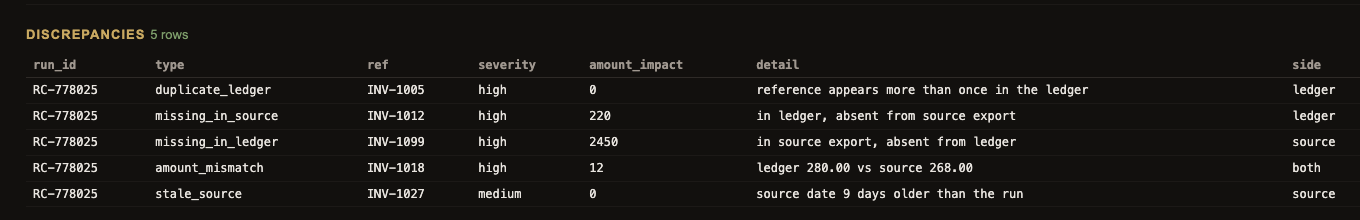
Run RC-778025, period 2026-09, materiality threshold 50 CAD. 41 ledger rows against 40 source rows, 39 matched references. Five findings: one duplicate, one ledger-only, one source-only, one amount mismatch, one stale source. Two findings are material and wait for sign-off. Variance is the sum of the affected amounts: 2,450.00 plus 220.00 plus 12.00.
Every finding has a rule
| Finding | Rule | In this run |
|---|---|---|
| duplicate_ledger | A reference appears more than once in the ledger | INV-1005 |
| missing_in_source | Ledger row has no source row | INV-1012, 220.00 |
| missing_in_ledger | Source row has no ledger row | INV-1099, 2,450.00 |
| amount_mismatch | Amounts differ by more than 0.50 tolerance | INV-1018, 12.00 |
| stale_source | Source date is more than 3 days older than the run | INV-1027, 9 days |
| sign_error | Sign differs between ledger and source | test case |
Each finding is written to the audit sheet with its type, severity, affected amount and a description. The summary row records the counts, the variance and how many items needed sign-off, so the next reader does not have to reconstruct the run.
What the reviewer gets
An email with the period, row counts, matched references, findings, variance and the count of material items. The email is a summary, not the evidence: the evidence is the audit sheet, where each finding keeps its reference and rule.
Where it fits
- Month-end and period-end reconciliation between an accounting export and an operational source.
- Any two-system comparison where "the totals are close" has replaced "the rows tie".
- A close process that needs a written sign-off trail without a new accounting system.